A three-digit number can decide whether you get a home loan, how much interest you pay on it, and sometimes even whether a landlord rents to you. Yet most people only check their credit score when an application is rejected. Understanding what drives it takes about ten minutes, and improving it is more predictable than you might think.
What a credit score measures
A credit score is a lender's shorthand for one question: how likely is this person to repay on time? Credit bureaus build it from your credit report — the record of your loans, credit cards, repayments and recent applications.
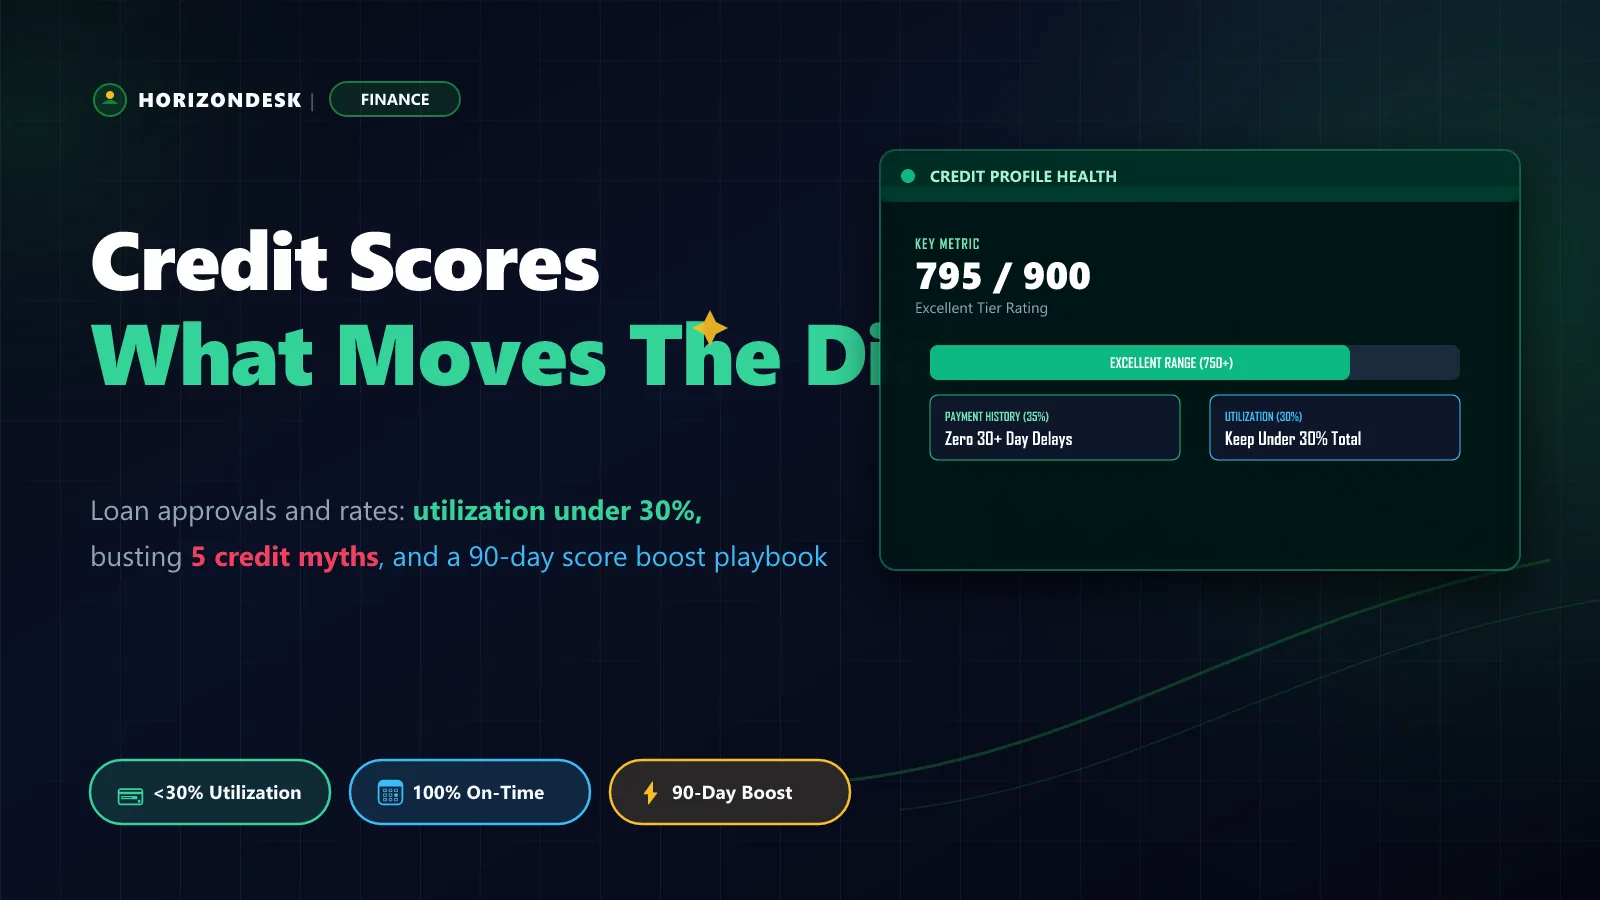
Scales differ by country. In India, bureau scores typically range from 300 to 900, and many lenders look for 750 or higher for their best rates. In the US, the widely used FICO score runs from 300 to 850. The principles behind them are remarkably similar.
Just as important is what a score doesn't include: your salary, your savings, your investments or your bank balance. A high earner with missed card payments can have a worse score than a modest earner who pays every bill on time.
The five factors that matter
Scoring models are proprietary, but they all weigh the same broad factors, listed here roughly in order of importance:
| Factor | What it means | How to improve it |
|---|---|---|
| Payment history | Whether EMIs and card bills are paid on time | Set up autopay for at least the minimum due |
| Credit utilisation | Card balances as a share of your total limit | Stay under 30%; under 10–20% is better |
| Length of history | Age of your oldest and average accounts | Keep your oldest card open and active |
| Credit mix | Balance of secured and unsecured credit | Let it develop naturally; never borrow just for mix |
| New credit | Recent applications and hard enquiries | Space out applications by several months |
Payment history dominates. A single payment more than 30 days late can stay on your report for years, which is why automating payments is the highest-value step you can take.
Your score doesn't reward wealth. It rewards being boringly reliable.
Five myths worth ignoring
- "Checking my score lowers it." Checking your own score is a soft enquiry and has no effect. Only lenders' hard enquiries, made when you apply, count.
- "A higher salary improves my score." Income isn't part of the calculation, though lenders consider it separately when deciding how much to lend.
- "Closing unused cards helps." Often the opposite. Closing a card reduces your total limit, which pushes up utilisation, and can shorten your credit history.
- "Paying the minimum due is fine." It prevents a late-payment mark, but the remaining balance attracts interest that on many cards works out to well over 30% a year.
- "Using a debit card builds credit." Debit cards draw on your own money and aren't reported to bureaus.
A 90-day plan to improve your score
Days 1–10: check your report for errors
Most countries entitle you to at least one free credit report a year from each bureau. Look for loans you don't recognise, accounts shown as open that you closed, and late payments you know were on time. Raise disputes with the bureau and the lender, and keep copies of everything.
Days 10–30: fix utilisation
The balance reported to bureaus is usually your statement balance, not what you pay later. Say your total card limit is ₹2,00,000 and you typically spend ₹80,000 a month — that's 40% utilisation, even if you pay in full. Pay ₹50,000 before the statement date and the reported figure drops to ₹30,000, or 15%. The same trick works on a $10,000 limit with $4,000 of spending.
Days 30–90: automate and wait
Set autopay on every card and loan, pause new credit applications, and let a few clean statement cycles accumulate. Utilisation improvements show up within a month or two; payment history builds over years.
There are no shortcuts, and anyone selling a quick fix is selling something you can do yourself for free. Pay on time, keep balances low, apply for credit sparingly — and your number will take care of itself.